How to Plan Seasonal Expenses and Avoid Budget Surprises

Everyone knows that moment: December arrives and the budget seems unable to cover the IPVA (annual vehicle tax), the holiday festivities, school enrollment, or that vacation trip. The problem is not a lack of income — it is that annual and occasional expenses rarely make it into the monthly plan. This article presents a practical method for recording future commitments, setting aside amounts gradually, and reviewing the plan frequently, so that predictable expenses do not turn into emergencies.
Why Seasonal Expenses Slip Out of Control
The traditional monthly budget considers fixed bills: rent, electricity, groceries, transportation. But seasonal expenses have different characteristics — they are predictable, yet spaced out. IPVA, IPTU (urban property tax), school supplies, gifts, car maintenance, annual insurance, subscriptions that renew once a year: all of these bills exist, but they do not show up on the month's spreadsheet.
The result is that, when the due date arrives, the amount competes with the current month's budget. To pay the IPVA, you cut back on groceries or use your credit card — and the debt stretches out. The solution is not to cut spending, but to change the logic: instead of paying when the bill comes due, you set aside a little every month, throughout the entire year.
Record All Future Commitments in One Place
The first step is to list everything you know you will spend over the next 12 months. This includes:
- Taxes and fees: IPVA, IPTU, vehicle licensing, extraordinary condominium fees
- Education: enrollment, school supplies, tuition that rises at the start of the year
- Dates and celebrations: birthday gifts, Mother's Day, Father's Day, Christmas
- Maintenance and insurance: car servicing, car or home insurance, tire replacement
- Subscriptions and renewals: annual plans, domains, software licenses
- Health: periodic check-ups, annual exams, vaccines, new glasses
- Travel and leisure: vacations, extended holidays, planned events
Use a simple spreadsheet with columns: description, expected month, estimated amount, actual amount (when paid), and status. The goal is not to get the amount right on the first try — it is to have visibility. A commitment recorded with an approximate value is already easier to plan for than a surprise on your bank statement.
A good reference for organizing this overview is the Central Bank's financial education material on personal budgeting, which addresses the importance of recording income and expenses in a structured way. You can consult it in the Sources section for further reading.
Calculate the Monthly Amount and Set It Aside Gradually
With the list ready, add up the total annual seasonal expenses. Say you have R$ 4,800 in annual expenses. Divide by 12: that is R$ 400 per month. This is the amount you need to set aside monthly to have the money available when the bill arrives.
The method works like this:
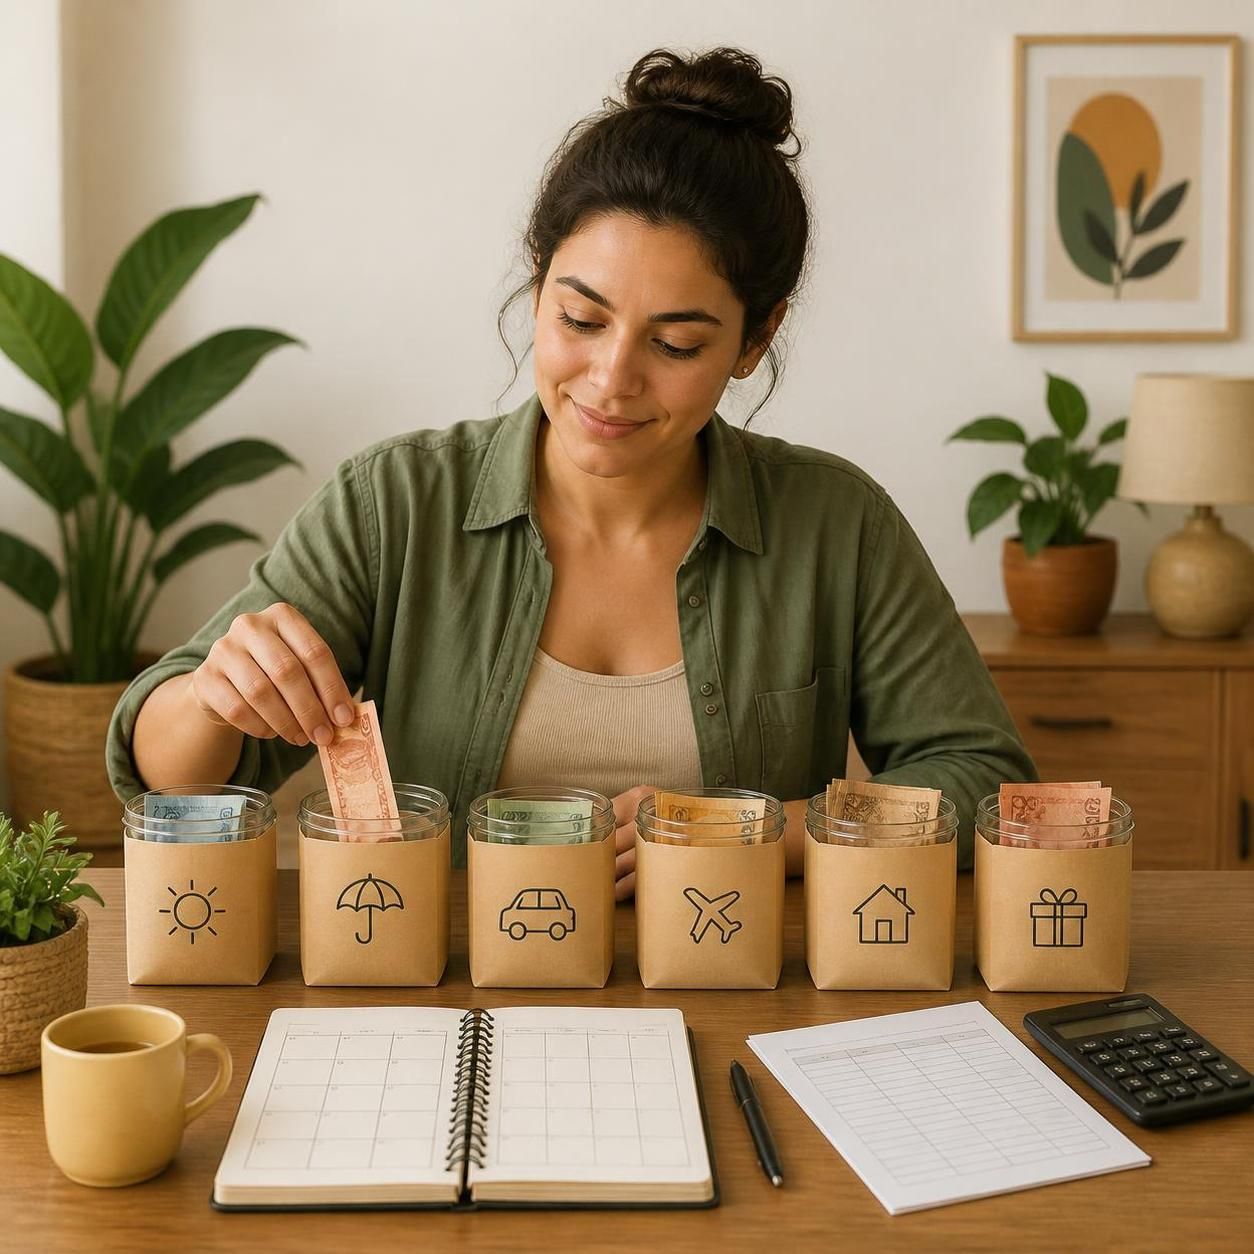
- Set up a separate account — it can be a simple savings account or a "piggy bank" in your bank's app. The important thing is to physically separate the money from the month's budget.
- Transfer the amount every month, right after payday — treat it like a fixed bill. If you pay your bills on the 5th, the reserve comes out on the 5th as well.
- Adjust when necessary — if an expense came out higher than expected, increase the reserve in the following months. If there was leftover, reduce it.
Illustrative Example
| Commitment | Expected month | Estimated amount |
|---|---|---|
| IPVA | January | R$ 1,200 |
| School supplies | January | R$ 600 |
| Car insurance | March | R$ 1,800 |
| Car maintenance | June | R$ 700 |
| Christmas gifts | December | R$ 500 |
| Annual total | — | R$ 4,800 |
Required monthly reserve: R$ 4,800 ÷ 12 = R$ 400/month.
If you start in October and the IPVA is due in January, you will have 4 months to set aside R$ 1,800 (IPVA + school supplies) — that is, R$ 450/month just for that period. The uniform monthly calculation works when you start at the beginning of the cycle; if you start mid-cycle, adjust the first few months.
Review the Plan Every Quarter
Seasonal expenses change. The IPVA can go up, insurance can get more expensive, the school can adjust tuition. That is why planning is not a static document — it is a cycle.
Every three months, set aside 30 minutes to:
- Check what has been paid and compare it with the estimate. If the difference was large, adjust the future amount.
- Update values for commitments that have changed (adjustments, new quotes).
- Add new expenses you had not anticipated (a wedding, a renovation, a course).
- Check the reserve balance — if it is accumulating more than necessary, reduce the monthly transfer and use the surplus for other goals.
The quarterly review is also the time to look at the following year. In September or October, do the survey for next year: research IPVA amounts, request insurance quotes, check the enrollment fee schedule. The sooner you know the numbers, the smoother the reserve adjustment will be.
Common Mistakes When Planning Seasonal Expenses
Underestimating amounts. Last year's IPVA is not a reference for this year. Always research the current amount before setting the estimate.
Mixing the reserve with the month's money. If the reserve stays in the same account as the current budget, it is tempting to use "just a little bit" to cover an unexpected expense. Separate it physically.
Starting in December. Planning in November for January's IPVA is the hardest scenario. The ideal is to start setting aside as soon as the expense is known — even if there is little time left, setting aside something is better than nothing.
Not reviewing. A plan made in January and forgotten until December will fail. The quarterly review is what keeps the plan aligned with reality.
Confusing it with an emergency budget. The seasonal expense reserve is not an emergency fund. They are different things: the seasonal reserve has a known date and amount; the emergency fund covers the unexpected. If you use the seasonal reserve for emergencies, you will run short when the due date arrives.
For related steps in a Brazilian household, see how to prepare a household budget and how to set financial goals.
Sources for Further Reading
This content is educational and does not constitute individual investment or credit advice. For further reading, consult:
- Central Bank of Brazil — Financial Education: Personal Budget: https://www.bcb.gov.br/pre/pef/port/folder_serie_II_orcamento_pessoal.pdf
- CVM — Step 3: Plan your expenses: https://www.gov.br/investidor/pt-br/investir/antes-de-investir/organize-a-sua-vida-financeira/passo-03-planeje-os-seus-gastos
If you do not yet have a structured family budget, it is worth starting with that before planning seasonal expenses — see our family budget guide. And if you want to turn the reserve into a larger goal, such as a trip or a down payment on an asset, the article on financial goals shows how to define timelines and amounts.
Applicable Summary
- List all annual and occasional expenses for the next 12 months in a spreadsheet.
- Add up the total and divide by 12 to know how much to set aside per month.
- Separate the money into a dedicated account or piggy bank, right after payday.
- Review the plan every quarter: adjust amounts, add new expenses, check the balance.
- Start now — even if there is little time before the first expense, setting aside something is better than nothing.
The secret is not earning more — it is giving visibility to what you already know you will spend. With record-keeping, gradual reserves, and periodic review, seasonal expenses stop being a surprise and become just another line in the budget.