
Salary portability in Brazil: what it is, how it works, and how to request it

You have the right to receive your salary in an account at any bank or payment institution authorized by the Central Bank of Brazil — not only at the bank chosen by your employer. This right is called salary portability (portabilidade de salário), it is guaranteed by Central Bank regulation, it is free of charge, and it can be canceled whenever you want. In this guide, you will understand how it works, how to request it, how long it takes, and what precautions to take.
What is salary portability
Salary portability is the possibility of transferring, at your request, the amount credited to your salary account to a deposit account or prepaid payment account in your name, either at the same institution or at another institution authorized to operate by the Central Bank of Brazil.
In practice: if your company deposits your salary at Bank A, but you prefer to receive it at Bank B (or at a digital bank), you can request portability and the amount will be transferred automatically to the account of your choice.
Salary portability in Brazil is regulated by CMN Resolution No. 5,058 of 2022, which governs the provision of salary payment services — including pensions, military pay, and similar remuneration — by financial institutions.
How it works in practice
The process is simple and does not depend on your employer's authorization:
- You choose the destination account: it can be an account at another traditional bank, a digital bank, or a payment institution, as long as it is authorized by the Central Bank and is in your name.
- You make the request in writing or by electronic means: the account designation is made as a standing instruction, and it can even be requested through the destination institution (the bank you want to move your salary to).
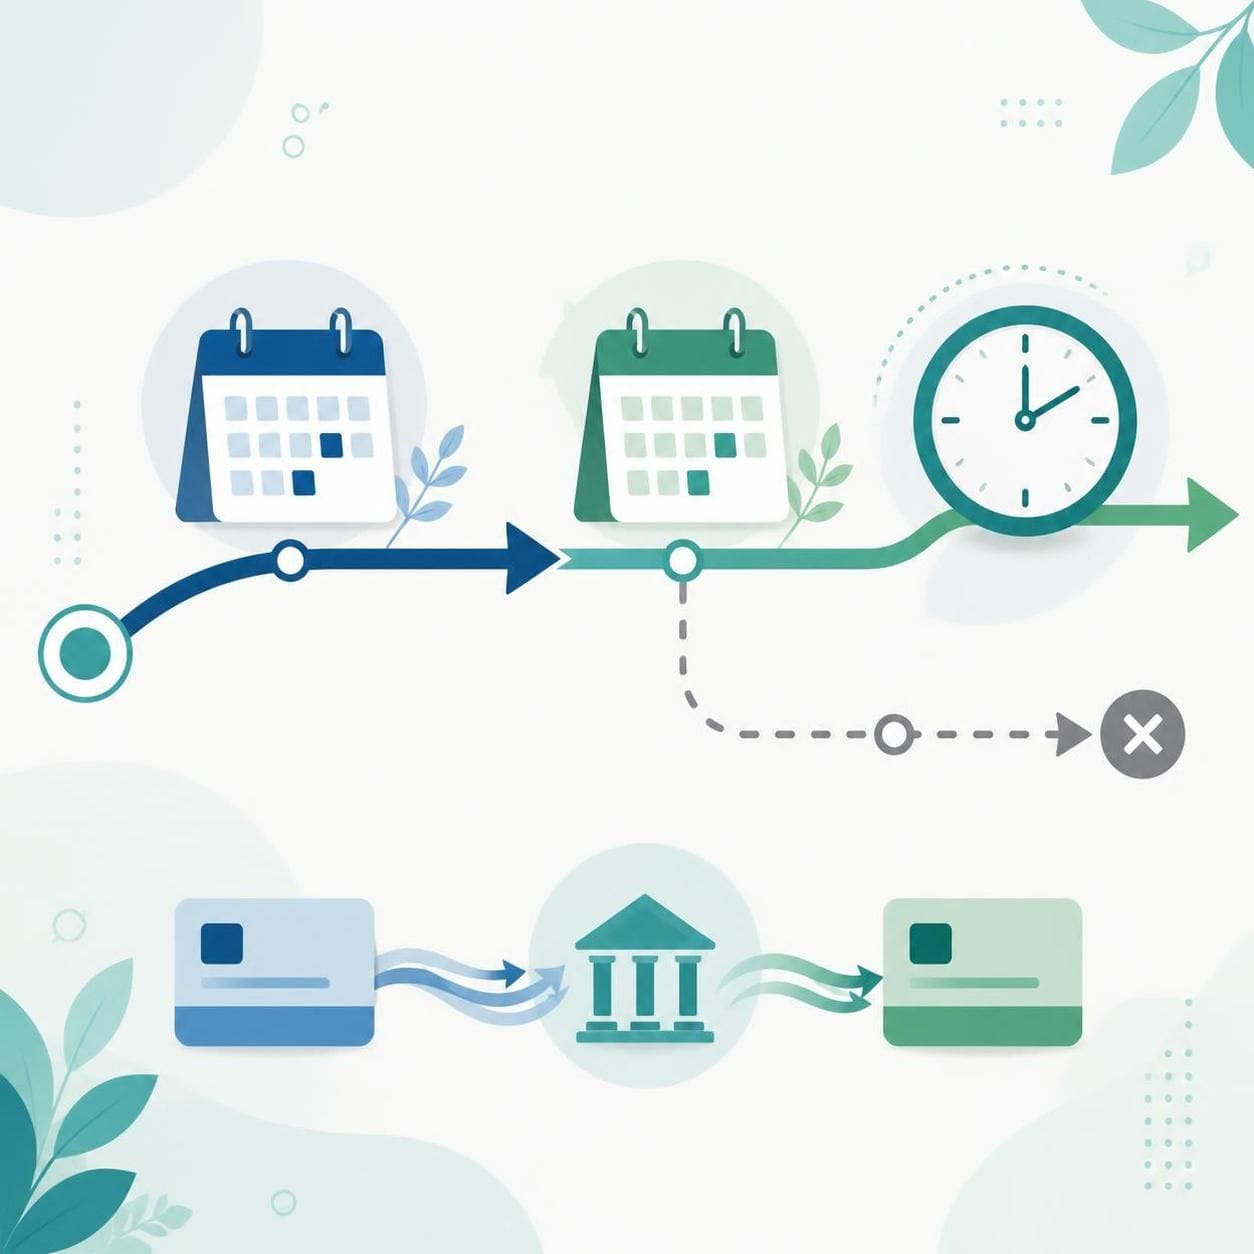
- The bank where you receive your salary has up to ten business days to process the request, counted from the date the request is received.
- From then on, your salary is transferred automatically to the chosen account, every month, without you needing to repeat the request.
Because the instruction is standing, the portability remains valid in the following months until you request its cancellation.
How much it costs
Nothing. Salary portability cannot generate any cost for the worker. The regulation expressly prohibits charging fees or reimbursing expenses to the beneficiary, both for requesting portability and for transferring the funds to other institutions.
If any bank tries to charge for this, it is a red flag: the service is your right, guaranteed by a Central Bank rule.
Which amounts are transferred
The transfer covers the total amount credited to the salary account. There is one important exception: if you have loan installments or leasing agreements with direct deduction from your salary credit, those installments may be deducted before the transfer. In other words, if you have a payroll-deducted loan (consignado) or financing linked to your salary account, check with the bank how this affects the amount that reaches the destination account.
How to cancel the portability
You can cancel the portability at any time. To do so, the cancellation request must be made at least five business days in advance, and the cancellation takes effect starting from the immediately following reference month. This deadline exists to give the system time to process the change before the next salary credit.
Why use (or not use) portability
Portability is a tool for freedom of choice. It makes sense when:
- Your current bank charges high fees on the salary account and another institution offers a fee-free account;
- You already concentrate your financial life at another bank and prefer not to keep transferring money manually;
- Another institution offers better conditions for your profile, such as cashback, integrated investments, or better customer service.
On the other hand, before porting, compare:
- Fees and costs of the destination account (remember that portability itself is free, but the destination account may have its own rules);
- Ease of use of the app and customer support;
- Whether you have credit or investments tied to your current account, which may be affected by the change.
Common mistakes to avoid
- Thinking you need your employer's authorization: portability is your right, activated directly with the financial institutions;
- Not checking the destination account's rules: check fees, limits, and conditions before porting;
- Forgetting automatic debits and linked credits tied to the old salary account;
- Confusing salary portability with bank portability: salary portability only deals with the salary credit; it does not automatically transfer other products or services.
FAQ
Does salary portability cost anything? No. Charging fees or reimbursing expenses from the worker for requesting portability and for transferring the funds is prohibited.
How long does it take for portability to take effect? The bank where you receive your salary has up to ten business days to process the request.
Do I need to notify my employer? The request is made in writing or by electronic means to the financial institutions, and can even be made through the destination institution. The rule does not require you to negotiate with your employer.
Can I cancel whenever I want? Yes. The cancellation takes effect starting from the following reference month, provided it is requested at least five business days in advance.
Can the transferred amount be partial? The transfer covers the total amount credited, with an allowance for the deduction of loan or leasing installments contracted by the beneficiary himself or herself.
Conclusion
Salary portability is a worker's right in Brazil — free of charge and reversible — regulated by CMN Resolution No. 5,058/2022. If you are unhappy with the bank where you receive your salary, evaluate the alternatives, check the fees and conditions of the destination account, and make the request — your current bank has up to ten business days to process it. And if it doesn't work out well, you can cancel at any time.
This content is educational and does not constitute individual investment or banking product advice.

