
What Is the CDI Rate: How It Works and Why It's the Benchmark for Investments

If you've ever researched CDBs, LCIs, or any fixed-income investment in Brazil, you've probably come across the acronym CDI. It shows up in phrases like "pays 100% of CDI" or "110% of CDI," yet many people invest without truly understanding what this rate means. In this guide, you'll learn what the CDI is, how it works, how it relates to the Selic rate, and why it's so widely used as a yield benchmark.
What Is the CDI?
The CDI (Certificado de Depósito Interbancário, or Interbank Deposit Certificate) is a security issued by banks to back very short-term loans between financial institutions themselves. In practice, banks lend money to one another for very short periods — usually one business day — and the rates on these transactions form an important market benchmark.
The average of the rates on these daily loans is called the DI Rate (Taxa DI), and it's this rate that serves as the reference for investments and financial products. When someone says an investment "pays the CDI," they're really talking about this benchmark rate — so much so that, in everyday use, "CDI" has become a colloquial synonym for the rate itself. The DI Rate is published by B3, the Brazilian exchange.
How the CDI Works in Practice
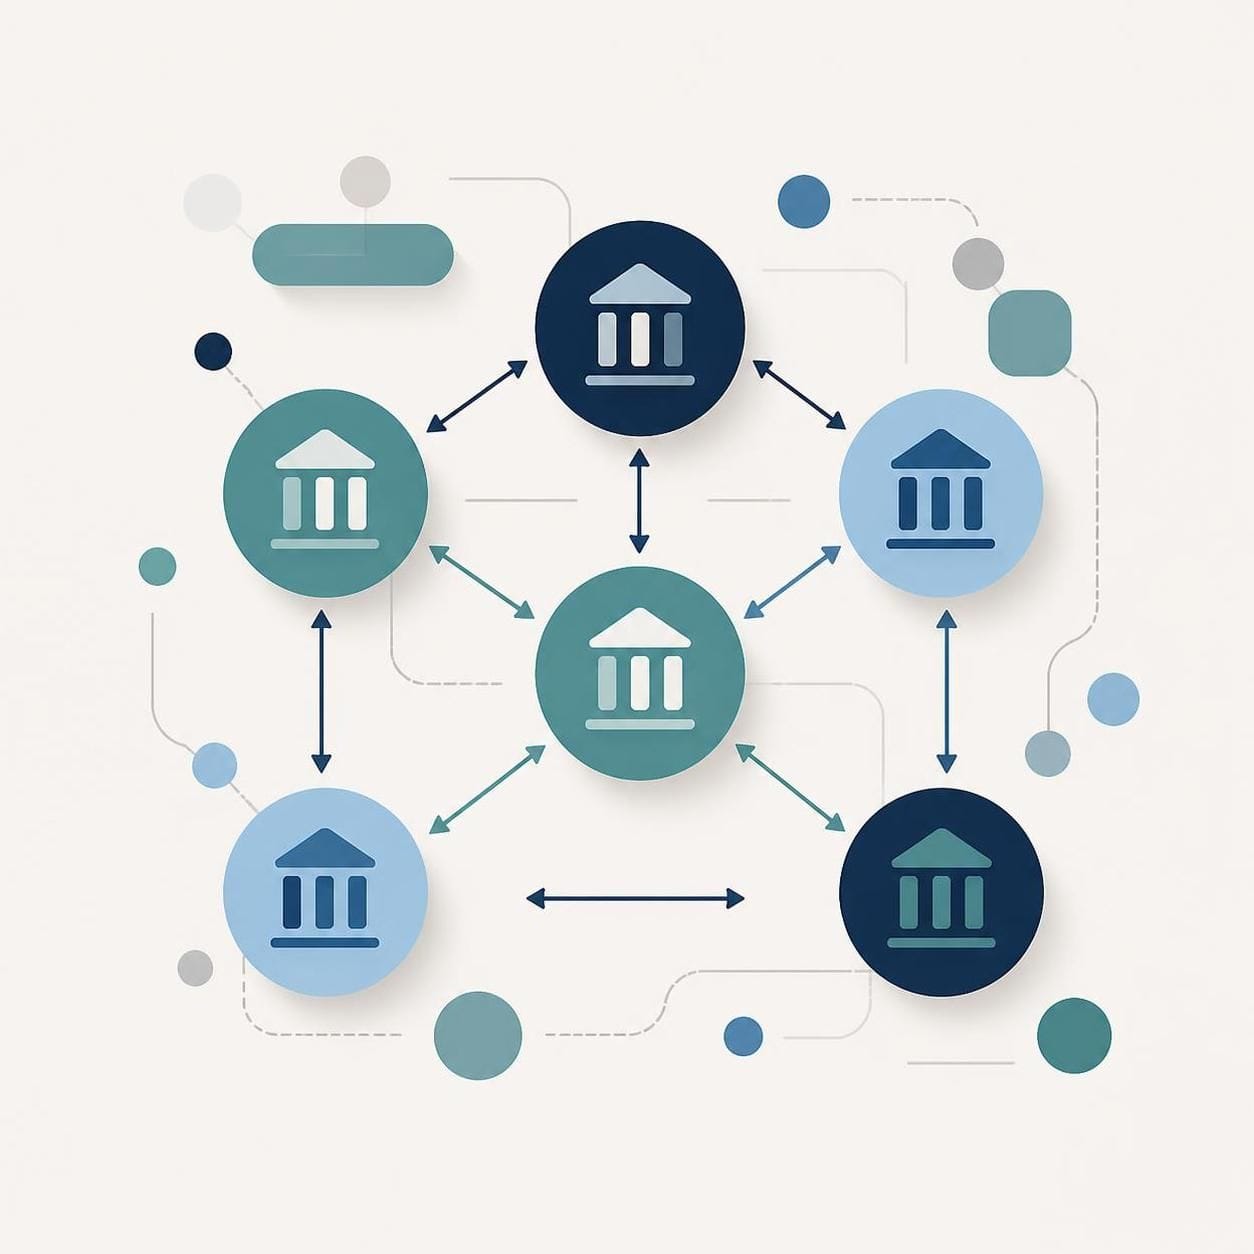
The interbank market exists because banks need to balance their cash on a daily basis. Some institutions end up with surplus funds while others face shortfalls. To rebalance, they carry out very short-term loans with one another, using the CDI as the security of the transaction itself.
Because these transactions happen every day and in large volume, the average of the rates charged has become a reliable thermometer for the cost of money in Brazil. That's why the DI Rate came to be used as the index for a wide range of fixed-income products.
CDI and Selic: What's the Relationship?
It's common to confuse the CDI and the Selic, and the confusion makes sense: the two rates tend to move together. Interbank loans backed by the CDI carry rates close to the Selic, Brazil's benchmark interest rate.
The relationship is one of tracking, not equality: when the Selic rises, the CDI tends to rise as well; when the Selic falls, the CDI tends to fall along with it. In other words, the CDI closely follows the direction of the Selic, staying at a very similar level.
For investors, this has a practical consequence: when the Central Bank raises the Selic, investments tied to the CDI tend to yield more; when the Selic falls, those same investments tend to yield less.
Why the CDI Is Used as a Yield Benchmark
Many fixed-income products — such as CDBs, LCIs, LCAs, debentures, CRIs, and CRAs — offer returns based on a percentage of the CDI, such as 80%, 100%, or even 120% of CDI. The higher the percentage, the higher the investment's return relative to the benchmark.
| Percentage of CDI | Practical reading |
|---|---|
| 80% of CDI | Delivers 80% of the benchmark rate over the period |
| 100% of CDI | Tracks the benchmark in full |
| 120% of CDI | Delivers 20% above the benchmark |
These percentages are illustrative examples of how the market typically expresses returns — not an offer, a simulation, or a promise of returns. Actual yield depends on the rate in effect in each period and on the specific terms of each product.
Where the CDI Shows Up in an Investor's Day-to-Day
You'll find the CDI as a reference mainly in:
- CDBs: many pay a percentage of the CDI, either fixed or tiered by term;
- LCIs and LCAs: bank-issued letters, also frequently tied to the CDI;
- Debentures, CRIs, and CRAs: corporate and real-estate/agribusiness securities that may use the CDI as their index.
If you're just starting to invest, it's worth understanding this benchmark well before comparing products. The fixed income guide and the article on how to start investing help put the CDI in the context of your portfolio.
The CDI and Comparing Investments
Because the CDI is a common benchmark, it makes comparisons easier. Instead of comparing nominal rates of different products at different moments, you can compare how many percentage points of the CDI each one delivers.
For example: a CDB paying 100% of CDI and another paying 90% of CDI can be compared directly by the difference in percentage, regardless of the rate's value at any given moment. The same reasoning appears when we compare CDBs, Treasuries, and savings accounts or analyze how much R$ 1,000 earns in a CDB.
Points to Watch: Liquidity, Taxes, and Protections
Before choosing any investment tied to the CDI, consider three dimensions beyond the advertised percentage:
- Liquidity: not every security allows redemption at any time. Check whether the product offers daily liquidity or has a lock-up period.
- Taxes: fixed-income investments in general follow Brazil's regressive income tax table, and very short redemptions may be subject to IOF. Rules vary by holding period and product.
- Protections: CDBs, LCIs, and LCAs are covered by the FGC (Brazil's deposit guarantee fund) within specific limits, which is worth understanding before investing meaningful amounts.
Remember: returns tied to the CDI vary with the rate in effect in each period. A benchmark or a past result does not guarantee future returns.
Common Mistakes When Evaluating Investments Quoted as a Percentage of CDI
- Looking only at the percentage: 100% of CDI with daily liquidity and 100% of CDI with a 3-year lock-up are not equivalent.
- Assuming CDI equals the Selic: the rates are close and tend to move together, but they are different things.
- Ignoring taxes and costs: the CDI percentage is gross; your effective return depends on the applicable taxation.
- Treating the percentage as a promise: the CDI is a benchmark that fluctuates; no percentage guarantees future returns.
FAQ
Are the CDI and the Selic the same thing? No. The CDI is an interbank loan security, and the DI Rate is the average of those rates — although, in everyday use, "CDI" has become a colloquial synonym for the benchmark rate. The Selic is Brazil's benchmark interest rate. They tend to sit at similar levels and move in the same direction, but they are distinct references.
What does a CDB paying 100% of CDI mean? It means the security's return tracks the benchmark rate for the period. If the CDI fluctuates over time, the return follows that fluctuation — it is not a fixed contracted rate.
Do investments tied to the CDI carry risk? Yes, like any investment. Beyond rate fluctuations, you need to consider issuer risk, liquidity, and taxation. Products with FGC coverage are protected only within the established limits.
Is the CDI good for an emergency fund? CDI-linked investments are often used for short-term goals precisely because they track the benchmark rate, but the choice depends on your profile, your timeline, and the specific terms of each product (liquidity, taxation, protections).
Conclusion
The CDI is the benchmark rate formed by very short-term loans between banks, and the DI Rate — its daily average — has become the main index for Brazilian fixed income. Understanding that it closely tracks the Selic, and that products like CDBs and LCIs pay percentages of this benchmark, helps you compare investments more clearly. When evaluating any product, look at the whole picture: the CDI percentage, liquidity, taxation, and protections — never a single number in isolation.
This content is educational and does not constitute individual investment advice or a promise of returns. Returns tied to the CDI vary with the rate in effect in each period; past performance or a benchmark does not guarantee future returns.
PARE após o corpo EN.

